The Charities VAT Compensation Scheme: Irish Charities
Updated 30 October 2026
Written for the 2026 VAT codes
This article uses the 2026 VAT codes that new customers are set up on. If your codes look like S1 - IE or P1 - IE, you are on the current codes: see Moving to the 2026 VAT Codes.
This article is for Irish charities using Aedon.Charities.
What the scheme is
Revenue refunds part of the VAT your charity pays and cannot reclaim in any other way. The refund depends on how much of your income is privately raised.
Who can claim
- Charities registered with the Charities Regulator that also hold a charitable tax exemption (CHY number) from Revenue, both when the VAT was paid and when you claim.
- Your charity also needs a current tax clearance certificate.
- Charities that are registered for VAT and those that are not.
- VAT you can reclaim on your VAT3, or under any other Revenue scheme, cannot be included.
How the claim is worked out
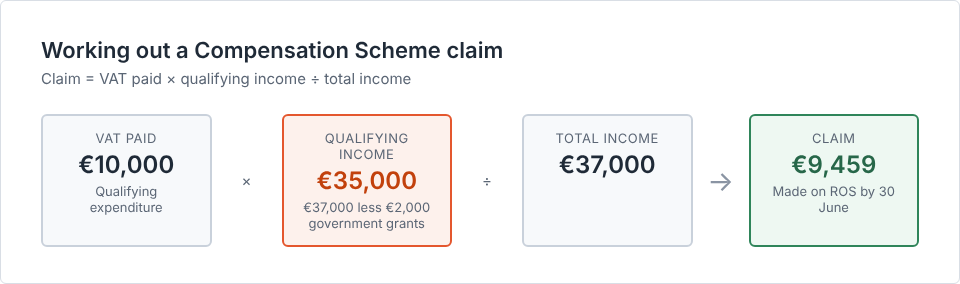
Claim = VAT paid × qualifying income ÷ total income.
| Example | Amount |
|---|---|
| Total income | €37,000 |
| Less government grants | €2,000 |
| Qualifying income | €35,000 |
| VAT paid on qualifying expenditure | €10,000 |
| Claim: €10,000 × 35,000 ÷ 37,000 | €9,459 |
Qualifying and non-qualifying income
| Qualifying income | Non-qualifying income |
|---|---|
| Donations, legacies, private grants and fundraising income | Government, HSE and local authority grants, Pobal funding, HAP and CES payments, Charitable Donation Scheme repayments and earlier VAT Compensation Scheme refunds |
Charity shop and café income are also treated as non-qualifying. Check the Revenue guidance for any income you are unsure about.
Dates and limits
- One claim a year, for VAT paid in the previous calendar year.
- Claims are made between 1 January and 30 June. Late claims are not accepted.
- The minimum claim is €500 and the maximum is €1,000,000.
- The fund is capped at €10 million a year. If claims exceed it, every charity receives the same percentage of its claim.
- Budget 2027 announced an increase in the fund to €15 million in 2027. Check the Revenue guidance for when it applies.
- Claims are made through ROS. Keep invoices and receipts for six years.
How Aedon helps
- At onboarding, tell us you claim under the Compensation Scheme, so the right codes are switched on.
- Code donations and private grants to
OOS-SAL-NA. - Code public funding and tax repayments to
OOS-SAL-NA-PUB. - Code each purchase at its VAT rate. If you are not registered for VAT, use
OOS-PUR-23,OOS-PUR-13.5orOOS-PUR-09. - Each January, run the Compensation Scheme report. It gives your total income, qualifying income and VAT paid for the previous calendar year, based on payment dates.
- Enter the figures in your claim on ROS by 30 June.
Useful Revenue links
- Revenue guidance: VAT Compensation Scheme for charities
- Revenue guidance: What is qualifying expenditure and qualifying tax?
- Revenue guidance: Making a claim
- Revenue Tax and Duty Manual Part 12: Charities VAT Compensation Scheme
Need help?
If you are unsure whether your charity qualifies, or how to treat a type of income, ask your accountant.
For help with Aedon.Accounting itself, please raise a case and our support team will help.
Related articles
Apportionment and Recovery Percentages: Irish Charities
Choosing the Right VAT Code: UK Charities
Claiming Gift Aid from HMRC
Donor Gift Aid Statements
Getting Started with Aedon.Charities
Gift Aid Declarations and Eligible Products