Choosing the Right VAT Code: UK Charities
Updated 31 October 2026
Written for the 2026 VAT codes
This article uses the 2026 VAT codes that new customers are set up on. If your codes look like S1, P1 or TP20, you are on the current codes: see UK VAT Codes (Tax Codes) and Moving to the 2026 VAT Codes.
This article is for UK charities set up on the 2026 VAT codes.
Every transaction you enter needs a VAT code. The code tells Aedon how to treat the VAT on your VAT return. The right code first time means a correct return and the right amount of VAT reclaimed.
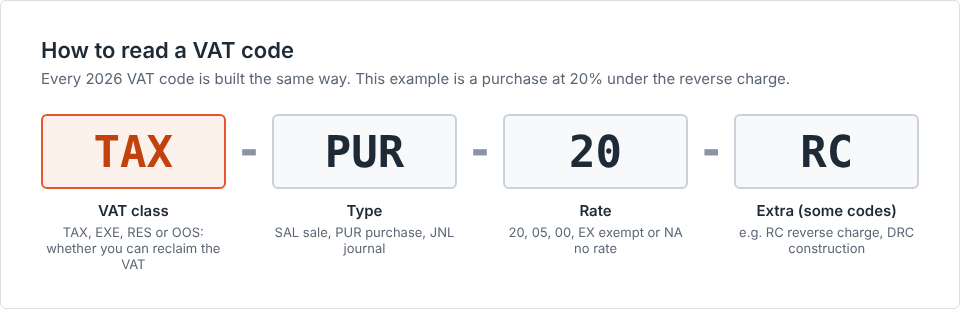
How to read a VAT code
Take TAX-PUR-20 as an example:
- TAX is the VAT class. It tells Aedon whether you can reclaim the VAT.
- PUR means a purchase. SAL means a sale, and JNL a journal.
- 20 is the VAT rate. EX means exempt, and NA means no rate applies.
A few codes have a fourth part, such as RC for reverse charge.
The four VAT classes
| VAT class | What it means | Can you reclaim the VAT? |
|---|---|---|
| TAX, Taxable | Sales that carry VAT at 20%, 5% or 0%, and what you buy only to make them | Yes, in full |
| EXE, Exempt | Exempt income, such as fundraising events, education or care fees, and what you buy only for it | No |
| RES, Residual | Overheads that support more than one type of activity | In part |
| OOS, Outside the Scope | Donations, grants, wages, and the costs of free activities | No |
Your everyday codes
| Code | Use it for | Examples |
|---|---|---|
TAX-SAL-20 |
Sales at 20% | Bought-in merchandise, sponsorship with advertising, paid training, trading subsidiary sales |
TAX-SAL-05 |
Sales at 5% | Rarely used by charities |
TAX-SAL-00 |
Sales at 0% | Sale of donated goods in a charity shop, sales of books |
EXE-SAL-EX |
Exempt income | One-off fundraising events, welfare services, education and training, room hire |
EXE-SAL-EX-INT |
Interest you receive | Interest on reserves and deposit accounts |
OOS-SAL-NA |
Income that is not a sale | Donations, legacies, Gift Aid, grants with nothing given in return |
TAX-SAL-NA-ADJ |
Correcting sales VAT from an earlier return | See Correcting VAT below |
TAX-PUR-20 |
Purchases at 20% for your taxable activities | Stock for the shop, card terminal rental |
TAX-PUR-05 |
Purchases at 5% for your taxable activities | Children’s car seats bought to sell in your shop |
TAX-PUR-00 |
Purchases at 0% | Food, books, charity advertising |
TAX-PUR-EX |
Purchases with no VAT because they are exempt | Bank charges, insurance, postage stamps, loan interest |
TAX-PUR-NA-ADJ |
Correcting purchase VAT from an earlier return | See Correcting VAT below |
OOS-PUR-NA |
Payments that are not for goods or services | Grants you pay to other organisations |
OOS-JNL-NA |
Journals with no VAT | Wages, PAYE, transfers between accounts |
Commonly miscoded items
| Item | Use | Do not use |
|---|---|---|
| Bank charges and account fees | TAX-PUR-EX |
TAX-PUR-20 or OOS-JNL-NA |
| Card terminal rental | TAX-PUR-20, where the invoice shows VAT |
TAX-PUR-EX |
| Card transaction fees | TAX-PUR-EX, unless the invoice shows VAT |
TAX-PUR-20 |
| Interest received on reserves | EXE-SAL-EX-INT |
OOS-SAL-NA |
| Interest paid on loans and overdrafts | TAX-PUR-EX |
OOS-JNL-NA |
| Donations | OOS-SAL-NA |
EXE-SAL-EX |
| Gift Aid repayments from HMRC | OOS-SAL-NA |
EXE-SAL-EX or TAX-SAL-00 |
Free activities and shared costs
These codes are switched on if your charity provides services free or below cost, or has exempt income as well as taxable sales.
| Code | Use it for | Examples |
|---|---|---|
OOS-PUR-20 |
Costs used only for free activities, with VAT at 20% | Printing a free information leaflet, a free helpline’s phone bill |
OOS-PUR-05 |
Costs used only for free activities, with VAT at 5% | Fuel and power for a free drop-in centre |
EXE-PUR-20 |
Costs used only for exempt income, with VAT at 20% | Venue hire for a fundraising event |
RES-PUR-20 |
Overheads shared across your activities, with VAT at 20% | Head office rent, audit fee, finance system |
You cannot reclaim VAT on costs for free activities. For shared overheads, Aedon works out how much you can reclaim at each VAT return. It uses your business percentage and recovery percentage, which your accountant agrees with you.
For example, your head office electricity carries £1,000 of VAT. With a 60% business percentage and a 70% recovery percentage, you reclaim £420.
Read Partial Exemption and Recovery Percentages: UK Charities for how the percentages work.
Other extra codes
Aedon switches these on when your account is set up, if they apply to you. If your charity’s work changes, please raise a case and our support team will switch the group on.
| Group | Switched on if you | Example code | Read more |
|---|---|---|---|
| Flat Rate Scheme | Use the VAT Flat Rate Scheme, which is rare for charities | TAX-SAL-20-FRS |
The VAT Flat Rate Scheme: UK Charities |
| International | Buy services from overseas suppliers, such as software or online fundraising platforms, or sell abroad | TAX-PUR-20-RC |
Reverse Charge VAT: UK Businesses |
| Construction | Carry out building work for others under the construction reverse charge | TAX-SAL-00-DRC |
Reverse Charge VAT: UK Businesses |
| Northern Ireland | Move goods between Northern Ireland and the EU | TAX-SAL-00-NIG |
Correcting VAT from an earlier return
- If a supplier sends a credit note, enter it with the same code as the original invoice.
- To correct VAT from an earlier return, post a VAT adjustment journal. Use
TAX-PUR-NA-ADJfor purchases orTAX-SAL-NA-ADJfor sales. - Enter the VAT amount. Enter a net amount only if your purchase or sales total also needs correcting.
- Record the original VAT period and the reason.
For example, a June invoice had £200 of VAT left off your return. In September, post one journal on TAX-PUR-NA-ADJ for £200 of VAT and £0 net.
Aedon warns you if your corrections for a period pass the HMRC limit. Larger errors must be reported to HMRC separately, so speak to your accountant.
If you are not registered for VAT
You do not file VAT returns, and you use three codes:
| Code | Use it for |
|---|---|
OOS-SAL-NA |
All income, including donations and Gift Aid |
OOS-PUR-NA |
All purchases, entered at their full cost including any VAT |
OOS-JNL-NA |
Wages, transfers and journals |
Useful HMRC links
- HMRC VAT Notice 701/1: How VAT affects charities
- HMRC guidance: Fundraising events: exemption for charities and other qualifying bodies
- HMRC guidance: VAT rates on different goods and services
- HMRC VAT Notice 706: Partial exemption, including non-business use
- HMRC VAT Notice 700/12: How to fill in and submit your VAT Return
- HMRC VAT Notice 700/45: How to correct VAT errors and make adjustments or claims
Need help?
If you are unsure which code to use, ask your accountant. A wrong code can mean reclaiming VAT you are not entitled to.
For help with Aedon.Accounting itself, please raise a case and our support team will help.
Related articles
Apportionment and Recovery Percentages: Irish Charities
Claiming Gift Aid from HMRC
Donor Gift Aid Statements
Getting Started with Aedon.Charities
Gift Aid Declarations and Eligible Products
Partial Exemption and Recovery Percentages: UK Charities