The VAT Flat Rate Scheme: UK Charities
Updated 30 October 2026
Written for the 2026 VAT codes
This article uses the 2026 VAT codes that new customers are set up on. If your codes look like S1, P1 or TP20, you are on the current codes: see UK VAT Codes (Tax Codes) and Moving to the 2026 VAT Codes.
This article is for UK charities on the VAT Flat Rate Scheme.
What the scheme is
Under the Flat Rate Scheme, you pay HMRC a fixed percentage of your VAT-inclusive turnover. You charge VAT at the normal rates, but you do not reclaim VAT on your purchases, except on some capital goods.
Is it right for a charity?
The scheme rarely suits charities:
- You cannot reclaim VAT on your costs, including the VAT on your taxable activities.
- Exempt income, such as rent or fundraising events, is taxed at your flat rate.
- Charities that usually receive VAT repayments from HMRC lose them.
Ask your accountant before joining.
Who can use it
- You can join if you expect your taxable turnover, excluding VAT, to be £150,000 or less in the next year.
- You must leave if your total income, including VAT, passes £230,000 in a year.
Your flat rate percentage
- Your percentage depends on your trade sector. HMRC publishes the list of sectors and rates.
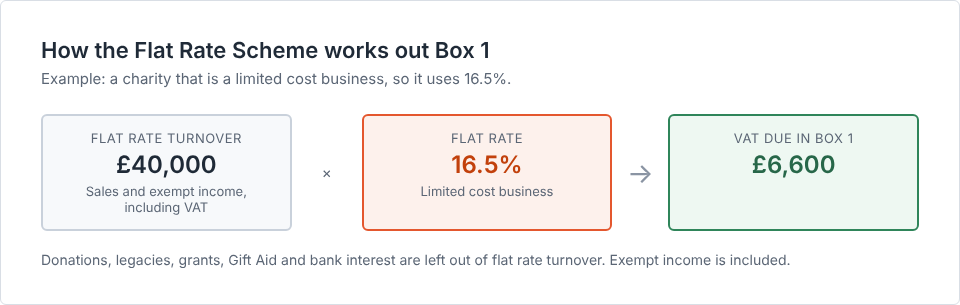
- If you are a limited cost business, you use 16.5%. You are a limited cost business if your spend on relevant goods is less than 2% of your turnover, or less than £1,000 a year. For a quarterly return the £1,000 becomes £250.
- In your first year of VAT registration, you take 1% off your percentage.
Your codes
| Code | Use it for |
|---|---|
TAX-SAL-20-FRS |
Sales at 20%, such as bought-in merchandise or sponsorship |
TAX-SAL-05-FRS |
Sales at 5% |
TAX-SAL-00-FRS |
Sales at 0%, such as donated goods sold in a charity shop |
EXE-SAL-EX-FRS |
Exempt income, such as fundraising events or room hire |
TAX-PUR-NA-FRS |
Purchases. You do not reclaim the VAT |
TAX-PUR-20-FRC |
Capital goods bought in a single purchase of £2,000 or more including VAT |
Keep donations, legacies, grants and Gift Aid on OOS-SAL-NA, and bank interest on EXE-SAL-EX-INT.
What goes into flat rate turnover
| Included | Left out |
|---|---|
| Sales at 20%, 5% and 0%, including the VAT | Donations, legacies and Gift Aid |
| Exempt income, such as fundraising events and rent | Grants with nothing given in return |
| Sales of capital goods on which you did not reclaim VAT | Bank interest |
Aedon works out Box 1 by applying your flat rate percentage to your flat rate turnover.
What is accounted for outside the scheme
- VAT on capital goods of £2,000 or more, which you reclaim in Box 4.
- Reverse charge services bought from overseas, such as software or fundraising platforms, which go in Boxes 1 and 4 as normal. See Reverse Charge VAT: UK Businesses.
- Postponed import VAT, which is added to Box 1 after the flat rate calculation. The value of the imported goods is left out of your flat rate turnover, and you can’t reclaim the import VAT in Box 4 unless the goods are a single purchase of capital goods costing £2,000 or more including VAT.
Useful HMRC links
- Revenue and Customs Brief 3 (2022): postponed VAT accounting and the Flat Rate Scheme
- HMRC VAT Notice 733: Flat Rate Scheme for small businesses
- HMRC guidance: VAT Flat Rate Scheme, flat rates for types of business
- HMRC VAT Notice 701/1: How VAT affects charities
Need help?
Ask your accountant whether the scheme suits your charity.
For help with Aedon.Accounting itself, please raise a case and our support team will help.
Related articles
Apportionment and Recovery Percentages: Irish Charities
Choosing the Right VAT Code: UK Charities
Claiming Gift Aid from HMRC
Donor Gift Aid Statements
Getting Started with Aedon.Charities
Gift Aid Declarations and Eligible Products