Partial Exemption and Recovery Percentages: UK Charities
Updated 30 October 2026
Written for the 2026 VAT codes
This article uses the 2026 VAT codes that new customers are set up on. If your codes look like S1, P1 or TP20, you are on the current codes: see UK VAT Codes (Tax Codes) and Moving to the 2026 VAT Codes.
This article is for UK charities that are registered for VAT and have free activities, exempt income, or both.
What this means for a charity
A VAT-registered charity can only reclaim VAT on costs used for its taxable activities. There are two limits:
- Non-business activities. VAT on costs for free or below-cost services funded by donations and grants can never be reclaimed.
- Exempt activities. VAT on costs for exempt income, such as fundraising events, education or care, cannot normally be reclaimed.
Your codes
| Code | Use it for | Example |
|---|---|---|
TAX-PUR-20 |
Costs used only for taxable activities | Stock for the charity shop |
OOS-PUR-20 |
Costs used only for free activities | Printing a free information leaflet |
EXE-PUR-20 |
Costs used only for exempt activities | Venue hire for a fundraising dinner |
RES-PUR-20 |
Overheads shared across your activities | Head office rent, audit fee, finance system |
RES-PUR-20-RC |
Overhead services bought from overseas | Software subscriptions from a non-UK supplier |
There are 5% and 0% versions of these codes. Aedon posts RES-PUR-NA-PEA itself, so you never enter it manually.
The two percentages
Shared overheads go through two steps:
- Business percentage. The share of your activity that is business, rather than free activity. Your charity chooses a fair and reasonable way to work it out, such as income, staff time or floor area, and uses it consistently.
- Recovery percentage. The share of your business activity that is taxable. Under the standard method this is taxable income ÷ total business income, rounded up to the next whole number.
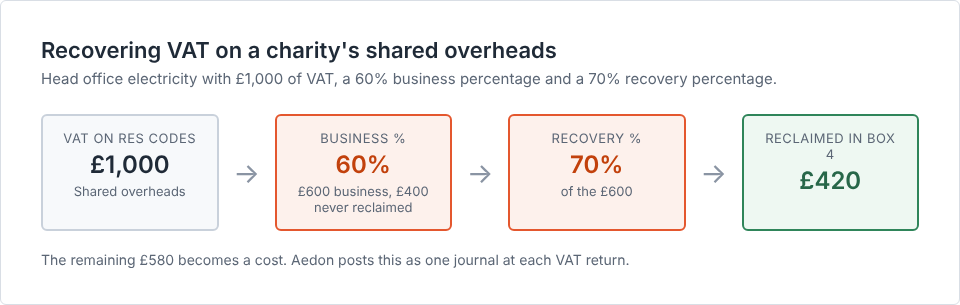
For example, head office electricity carries £1,000 of VAT. With a 60% business percentage, £600 is business and £400 is never reclaimed. With a 70% recovery percentage, you reclaim £420 of the £600.
The combined method
A charity can ask HMRC to approve one combined method that replaces both percentages. HMRC must approve it in writing. Under a combined method, the de minimis test does not apply.
What Aedon does at each VAT return
- Adds up the VAT on your RES codes.
- Applies your business percentage, then your recovery percentage.
- Posts one journal that puts the VAT you can reclaim in Box 4 and the rest into costs.
- Checks the de minimis test, unless you use a combined method.
The de minimis test
You can reclaim the exempt part of your VAT if your exempt VAT is both:
- no more than £625 a month on average, and
- no more than half of all your input VAT.
There is no de minimis for VAT on non-business activities.
The annual adjustment
At the end of your partial exemption year, the percentages are worked out again on the whole year’s figures. The difference is posted on the last return of the year, or the first return after it.
What we need from your accountant
| Setting | Example |
|---|---|
| Business percentage, and how it is worked out | 60%, by staff time |
| Method | Standard, special or combined |
| Partial exemption year end | 31 March |
| Current recovery percentage | 70% |
| Return for the annual adjustment | First return after the year end |
| Include non-business costs in Box 7 | Yes, the default |
Useful HMRC links
- HMRC VAT Notice 706: Partial exemption, including section 7 on non-business use
- HMRC VAT Notice 701/1: How VAT affects charities
- HMRC guidance: Apply for a partial exemption special method
Need help?
Ask your accountant about your method and percentages.
For help with Aedon.Accounting itself, please raise a case and our support team will help.
Related articles
Apportionment and Recovery Percentages: Irish Charities
Choosing the Right VAT Code: UK Charities
Claiming Gift Aid from HMRC
Donor Gift Aid Statements
Getting Started with Aedon.Charities
Gift Aid Declarations and Eligible Products